+63%1
PC-IOL unit sell-out
Versus +3% for the same portfolio · 2024–2025
Category growth outpaced the overall portfolio.
For IOL companies
Your launch can win attention without changing routine practice. Identify what is holding adoption of your product back, test the right clinic support and give your market team evidence for its next investment.
Hands-on IOL market-building experience meets direct patient conversations, education and research. The work can cover an existing product, a new launch or a defined cohort of partner clinics.
The result your team needs
A product-specific question, a defined market and a useful next decision. Category growth alone does not tell you whether your own IOL is gaining use.
Separate a positioning problem from clinic capability, access, patient understanding or the support model. Direct investment toward the actual constraint.
Translate product differentiation into an appropriate place in the pathway, with honest trade-offs and practical actions for field and clinic teams.
Measure defined product and clinic indicators. Learn whether to scale, revise or stop before committing to the next cohort or market.
Preparing a launch? Define the clinic pathway and adoption hypothesis before rollout. Clinical suitability, patient choice and your medical/regulatory review remain part of the work.
Documented commercial experience
Purchasing patterns from the ophthalmic distribution business I co-founded and chair: growth across the partner network, within established accounts and in repeat purchasing. A historical operating record—not proof of a guaranteed result in a new market.
+63%1
Versus +3% for the same portfolio · 2024–2025
Category growth outpaced the overall portfolio.
75%1
2025
Three in four across the active partner network.
+59%1
2024–2025
Higher recorded PC-IOL purchasing among accounts purchasing in both years.
+40%1
2024–2025
The number purchasing in at least six calendar months grew 40%.
PC-IOL means presbyopia-correcting IOL. Figures are distributor sell-out — not implantations, clinical outcomes or national market share. Repeat accounts recorded positive annual net PC-IOL sell-out in both years; routine accounts did so in at least six calendar months of a year.
Data on file. PDDA® Studio, Track Record Analysis TR-2026-01 (2026). Aggregated distributor sell-out and account cohorts from one market. This is an observed commercial record, not a controlled PDDA® study, implantation data, clinical outcomes or national market share. Underlying records are confidential.
Review data and definitionsHow we get there
Start with diagnosis if the barrier is unclear, or scope a defined pilot directly. These workstreams connect as needed; they are not a mandatory package of activities.
For a market launch or an established market, build an evidence-based view of how premium decisions are actually made — where the product enters the journey, where value is lost and how clinics experience the current support model.
Translate clinical differentiation into patient-relevant value, honest trade-off language and a communication structure that commercial teams and clinics can use without overclaiming.
Build a clinic activation pilot in selected clinics, align the field and clinic teams, measure early indicators and turn what works into a practical market-level growth playbook.
The starting point can vary, but the work is scoped around an adoption outcome and a market learning agenda — not around the production of individual marketing deliverables.
I can lead the defined programme or work alongside your existing field, clinical education and agency teams. The scope names the implementation owner, data requirements, deliverables and review points before work begins.
The complete patient journey
The product moves through a clinical and commercial value chain. The patient moves through a decision journey. Adoption depends on whether those two systems meet.
Before the clinic
Search, AI answers, brand and clinic content, patient stories and referral conversations shape what the patient expects and trusts.
The product is simplified, overpromised or never becomes personally relevant.
Where value changes hands
The brand narrative passes through local marketing, the clinic, staff and the surgeon — each adding interpretation and operational constraints.
Clinical differentiation arrives as a specification, not as usable decision support.
Inside the consultation
The patient must connect a clinically relevant option with their own visual priorities, understand the trade-offs and make a confident shared decision.
Fear, overload or an inconsistent offer sends the patient to the default.
Where value gets lost
Patient language is one part of the diagnosis. We also investigate product–market fit, access, clinic capability and the operating support around the offer.
Differentiation lives in optics, outcomes and technical language — but not in terms the patient can connect with real life.
The surgeon or counsellor has to invent the bridge from technology to value, differently in every clinic and every consultation.
A market may need different clinic support, better patient preparation or a change in the offer. More training cannot answer every adoption question.
Transfer and scale
Use a defined clinic cohort to learn what changes, what remains uncertain and whether wider rollout is justified. Expansion follows the evidence rather than being assumed.
Pilot → Playbook → Team enablement → Controlled rollout
The objective is an operating model the brand can own and govern — not permanent dependence on an external advisor.
Standard pilot scope: one market, one defined product/adoption hypothesis and one agreed clinic cohort. The pilot closes with a decision to scale, revise or stop; additional markets and wider rollout are separately scoped.
Production design, CRM or web implementation, translation, media buying and regulatory approval are not included unless separately agreed.
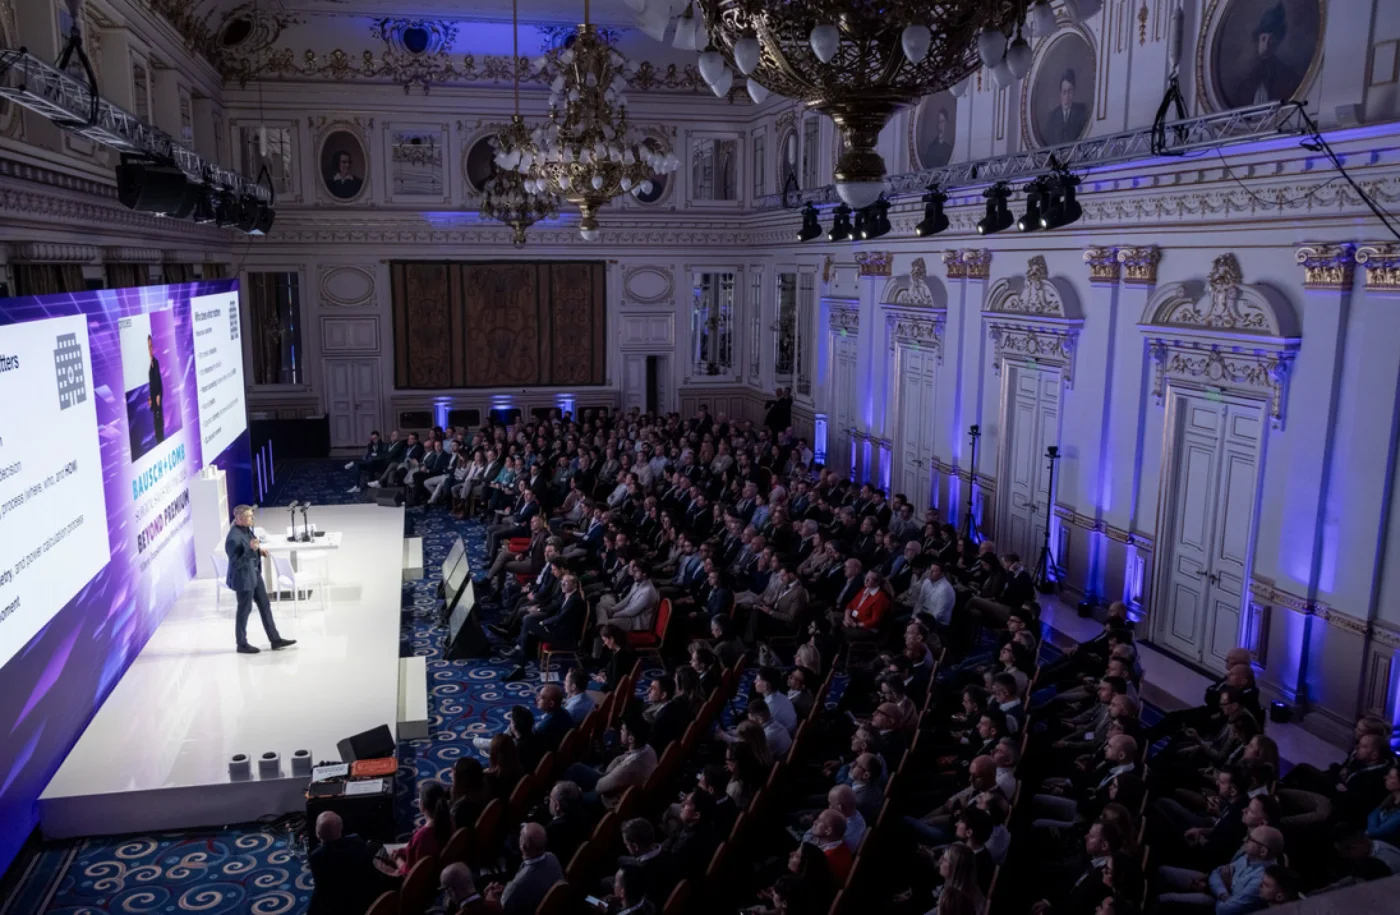
Invited keynote · Bausch + Lomb European Premium Transformation meeting · Budapest, 2026
Why work with me
I bring IOL commercial experience and first-party patient insight into the same project. Direct conversations, questionnaires and public-discussion research help us identify what needs checking with the target market and clinic team.
In ophthalmology since 1996, across technology, distribution, application and market development
Hands-on work with private clinics and the operational reality of premium pathways
22,700+ IOL questionnaire records from 65+ countries and territories
15M+ verified YouTube views across two patient-education channels
Commercial relationships and working boundaries
I co-founded and chair an ophthalmic distribution business operating in one European market; I have not been involved in its day-to-day operations since 2018.
I disclose relevant commercial relationships in every engagement and agree conflict boundaries before work begins. PDDA® does not prescribe a particular brand; product work is assessed against the approved evidence, patient needs and project brief. Brand-side advisory work excludes the distributor's market.
Engagement model
The first engagement is built around a specific market, product and adoption challenge. Ongoing advisory support makes sense after the model, responsibilities and implementation agenda are clear.
Start the conversation
A 20-minute introductory call to clarify the product, market and decision you need to make. We will discuss fit and next steps; detailed diagnosis is scoped separately.